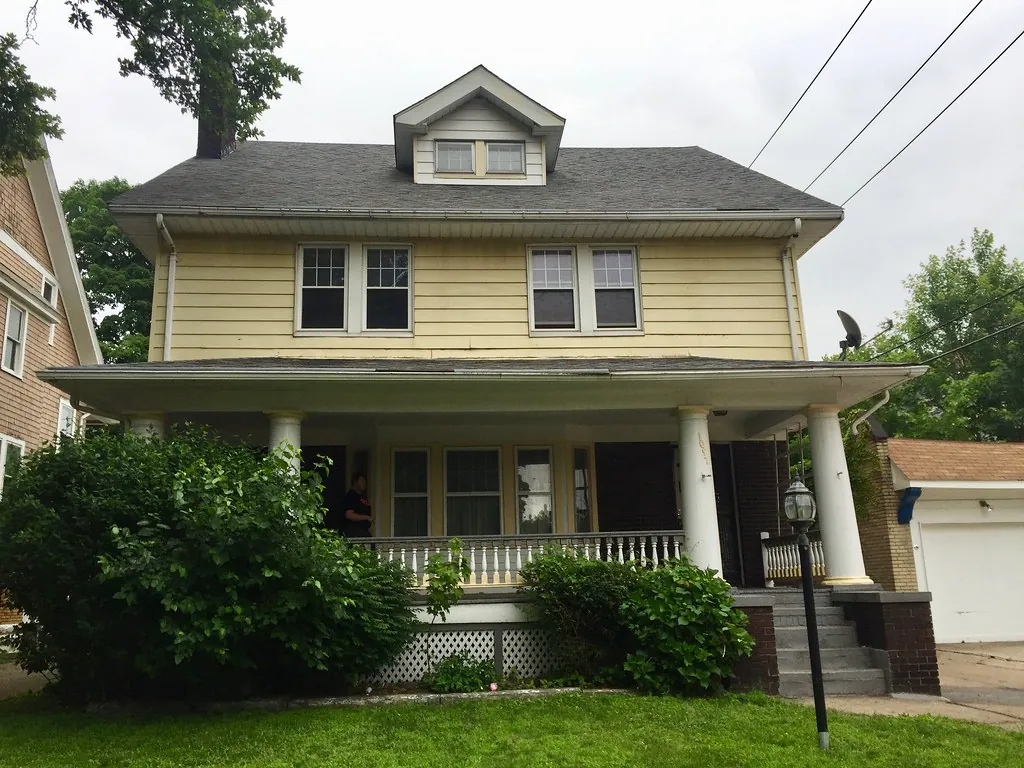
One state, very different houses
A homeowners estimate that works for a vinyl-sided house in Waldorf can miss badly on a brick rowhouse in Canton or a stone farmhouse outside Frederick. Most of the disputes we see come down to a desk estimate that treats every Maryland home as the same box. Here is how the housing stock changes the conversation.
Baltimore rowhouses
Many were built between the 1880s and the 1920s with low-slope membrane or built-up roofs, shared party walls and plaster interiors. Repairs often involve coordination with the neighbors on both sides, flashing that ties into adjoining roofs, and plaster work that can’t be swapped for a single coat of drywall without a visible mismatch. Our rowhouse roof claims guide covers the roof side in detail.
Mid-century colonials and Cape Cods
Towson, Catonsville and Bowie have large numbers of 1930s–60s homes with hardwood floors, original trim and older wiring. Partial repairs can trigger code upgrades, and matching flooring or trim across open rooms becomes a real cost item.
Planned-community townhouses and newer subdivisions
In Columbia, Waldorf and parts of Harford and Frederick counties, siding and shingle lines get discontinued quickly. When a replacement product won’t match, the question becomes how much of the elevation or roof plane has to be redone.
Lake cabins and second homes
Deep Creek Lake properties in Garrett County face heavy snow, freeze damage and access problems that raise labor costs. Seasonal vacancy can also bring heat and inspection conditions in the policy into play.
Where homeowner estimates usually fall short
| Part of the claim | Common gap |
|---|---|
| Dwelling (Coverage A) | Missing tear-out, undersized quantities, no overhead and profit on multi-trade jobs |
| Other structures (Coverage B) | Detached garages, fences and sheds priced as patch repairs |
| Personal property (Coverage C) | Heavy depreciation, items left off the inventory, cleaning versus replacement |
| Loss of use / ALE (Coverage D) | Displacement period shorter than the real rebuild schedule |
Depreciation deserves special attention. Many Maryland policies pay actual cash value first and release the rest once repairs are done. If the initial depreciation is too aggressive, the up-front check may not be enough to hire a contractor. The RCV and ACV holdback worksheet shows how much is being held back and why.
Condo owners and the master policy
If you own a unit in Ocean City, Silver Spring, Rockville or Harbor East, two policies are usually involved: the association’s master policy and your own HO-6. Which one pays for drywall, cabinets, flooring and fixtures depends on the condominium documents and the master policy’s definition of the building. Before anyone values the loss, we sort out which pieces belong to which policy, so you aren’t appraising items the other carrier is responsible for.
How a home appraisal file comes together
- A walk-through with you to understand what happened and what has been repaired already.
- Measurements, photos and moisture or material notes where they matter.
- An independent estimate priced for your county, not a national average.
- A side-by-side with the carrier’s estimate so the gap is easy to see.
Maryland Insurance Appraiser then advises whether the gap is large enough to justify demanding appraisal, or whether a documented supplement may close it. Either way, you get a valuation you can understand.
Homeowners sometimes worry that asking for appraisal will sour the relationship with their insurer. It is a process written into the policy itself, available to either side, and using it is simply a way to resolve a disagreement about numbers. If you have broader concerns about how your claim was handled, the Maryland Insurance Administration accepts consumer complaints.
Questions about home insurance appraisal
Can I use appraisal for a condo unit claim in Maryland?
Yes, if your HO-6 policy has an appraisal clause and the dispute is about the amount of a covered loss. The first step is confirming which items fall under your unit policy rather than the association’s master policy.
Does appraisal cover my additional living expenses?
If the insurer accepts that loss of use is covered but disputes the amount, those expenses can usually be submitted to appraisal along with the dwelling and contents figures. The policy wording controls.
Will appraisal help if my older Baltimore rowhouse has plaster walls?
It can, because plaster repair, matching and coordination with adjoining homes are valuation issues. An appraiser can document those costs so the panel isn’t comparing plaster work to a basic drywall patch.