Sudden water, slow leaks and floods are three different claims
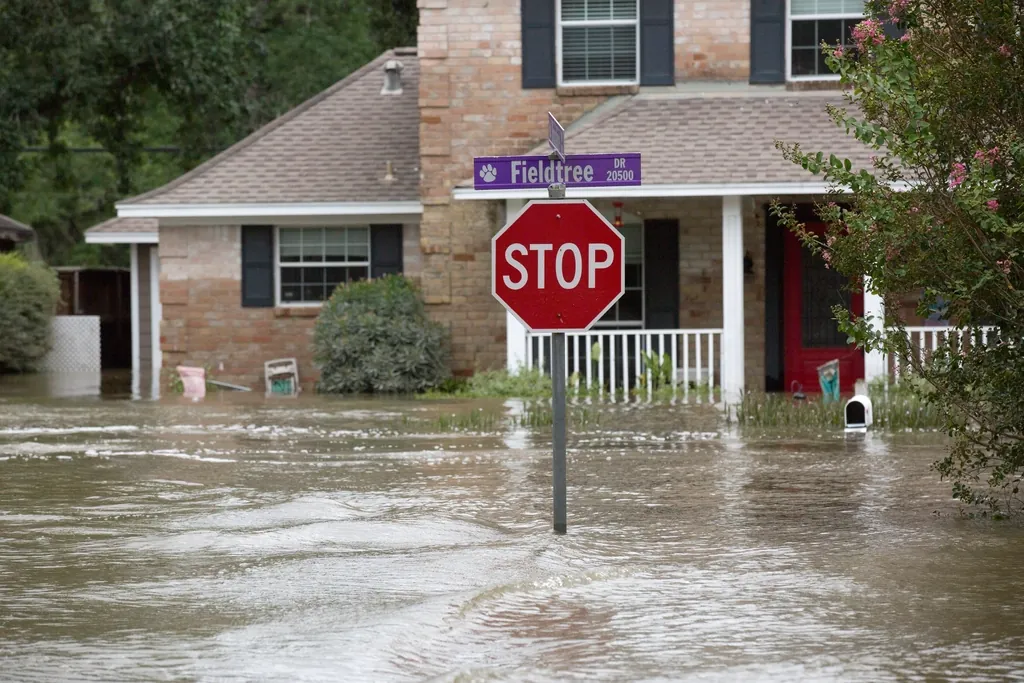
Water claims sort into categories before anyone gets to the dollars. A supply line that bursts behind a kitchen wall is usually treated as sudden and accidental. A drip that rotted a subfloor over many months may fall under a wear-and-tear or repeated-leakage exclusion. Water that came from outside – a stream overflowing in a flash flood, tidal flooding along the Bay – is generally a flood loss handled under a separate flood policy. The Ellicott City flash floods of 2016 and 2018 are a local reminder of how fast that kind of water arrives.
Appraisal deals with the first category: the covered loss whose amount is in dispute. If the insurer has said the leak was long-term, that is a coverage question, and it may need to be resolved before an appraisal makes sense.
Mitigation invoices and drying logs
Most covered water losses start with a mitigation company pulling wet materials, setting dehumidifiers and air movers, and monitoring moisture. Carriers often reduce those invoices, arguing that too much equipment was used or it stayed too long. To support the bill, the file needs:
- daily moisture readings for each affected area;
- equipment counts and placement maps;
- photos of the conditions when the crew arrived;
- notes on why particular materials were removed rather than dried in place;
- any containment or antimicrobial work and the reason for it.
An appraiser can value those services when they are documented. When they aren’t, we help reconstruct what can be supported from photos and records.
Plaster, hardwood and the matching problem
Older Maryland homes make water claims more expensive than a generic estimate assumes. Baltimore rowhouses and 1930s colonials in Towson and Catonsville often have plaster on lath, site-finished hardwood running through several rooms, and tall baseboards and casings that are no longer stocked.
Floors
Refinishing or replacing a few boards in a continuous oak floor can leave a visible line. Whether the floor must be redone to the next natural break is a valuation question a panel can decide.
Walls and ceilings
Plaster repairs require different labor than drywall, and blending a patch into an old textured ceiling may not be possible. The estimate should say how the wall will actually be repaired.
Cabinets and counters
Swollen base cabinets often can’t be replaced individually without mismatching the uppers, and stone counters may not survive removal.
What a water appraisal file includes
- A map of the water path from source to the lowest affected point.
- Room-by-room scope with removal, drying, rebuild and finishes.
- Contents list with cleaning versus replacement noted item by item.
- Additional living expense if the home was unlivable during repairs.
Maryland Insurance Appraiser often starts water files with a carrier estimate review so you can see where the gap is before deciding on appraisal. We handle water claims statewide, including older homes around Ellicott City where stone and plaster construction is common.
Keep the evidence
If you’re in the middle of a water loss now, photograph everything before it is removed, keep samples of flooring and trim where practical, and save every invoice. Those details are often what decides a disputed line item later.
Ask the mitigation company for its moisture maps and equipment logs before the job closes, not months afterward, and keep a simple diary of the days you were out of the house. Records made at the time carry more weight with a panel than recollections assembled once the walls are closed up again.
Questions about water damage appraisal
Will appraisal cover water damage from the Ellicott City type of flash flood?
Flash flooding from outside the home is usually a flood loss, which standard homeowners policies exclude. Those claims typically go through an NFIP or private flood policy, which has its own dispute process.
My insurer cut the mitigation company’s bill. Can that be appraised?
If the insurer accepts the water loss and disputes what the drying work was worth, that amount can usually be submitted to appraisal. Moisture logs and equipment records are the key evidence.
Can appraisal require my whole hardwood floor to be refinished?
Appraisal sets the cost of a reasonable repair. If refinishing only the damaged area would leave an obvious mismatch in a continuous floor, the panel can consider that in deciding the amount.