Maryland wind events that shape claims
Maryland doesn’t get many headline tornadoes, but wind losses are routine. Three events still come up when people talk about wind claims here:
- The La Plata tornado, April 28, 2002. An F4 that cut through Charles County and the town of La Plata, a reminder that Southern Maryland can see violent tornadoes.
- The June 29, 2012 derecho. Straight-line winds swept across the state, toppling trees, damaging roofs and leaving many households without power for days.
- The September 1, 2021 tornado. Spawned by the remnants of Ida, it moved through Annapolis and Edgewater, damaging homes and businesses along its path.
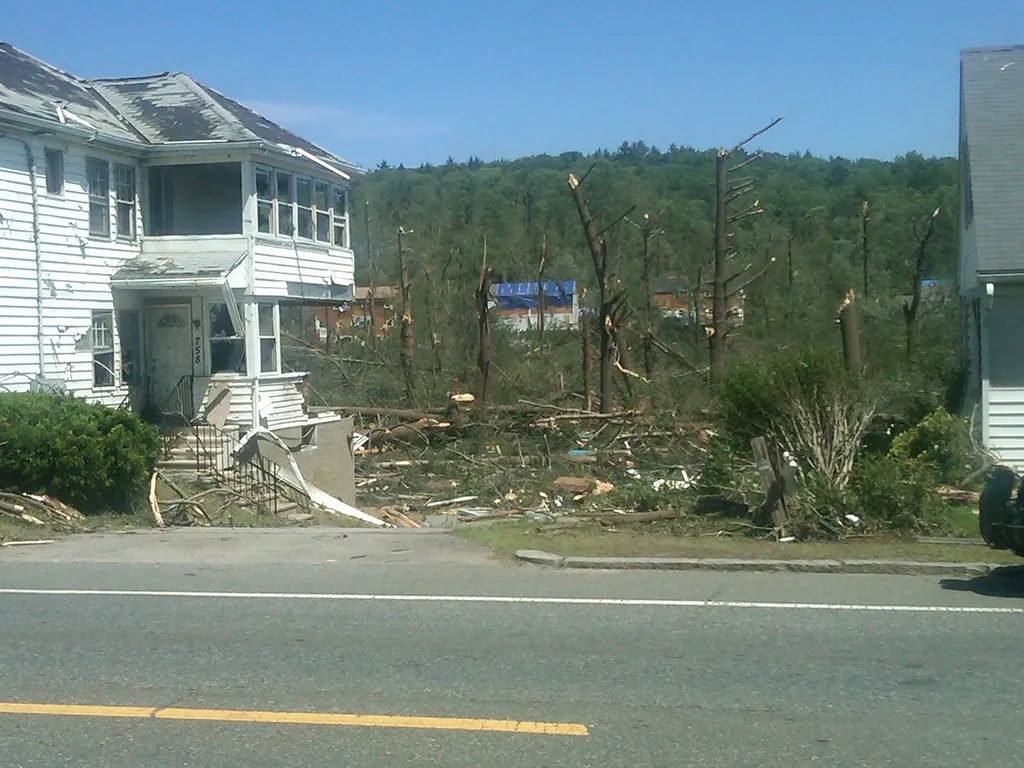
Most Maryland tornadoes are brief and fall in the EF0 to EF2 range, and most wind claims come from ordinary thunderstorm gusts. That makes wind damage easy to underestimate: the house is still standing, so the estimate covers a few shingles and a section of gutter.
What gets missed after a wind event
Wind works differently from hail. It pulls, twists and pressurizes, and the damage it leaves can be subtle. Common omissions in carrier estimates include:
- creased or unsealed shingles that look flat but have lost their bond;
- siding that has been pulled loose at the nailing strip on one elevation, with no matching product for a partial repair;
- racked fences, bent porch posts and lifted decking;
- sheathing and rafter damage under a roof that was “only” missing a few tabs;
- water intrusion through openings created during the storm;
- debris removal and temporary protection such as tarping and board-up.
In tornado and derecho files, falling trees are often part of the loss too. Our tree impact claim appraisal page covers removal limits and structural repairs.
Building a wind estimate that holds up
For a panel to accept a wider scope, the estimate has to show why the damage is storm-related and why the repair has to be as large as it is. On wind files we focus on:
- Directional damage patterns that line up with the storm’s track and the reported wind direction.
- Close-up photos of creases, torn mat and failed seals on each slope.
- Siding and trim product identification, so matching can be addressed with evidence.
- Framing checks in the attic or behind removed finishes where the structure may have moved.
- Emergency services invoices tied to dates and actual work.
Maryland Insurance Appraiser works wind and tornado files throughout the state, from Annapolis waterfront neighborhoods to subdivisions around Waldorf in Charles County.
Timing after a storm
After widespread wind events, contractors and adjusters are stretched thin, and early estimates are often written quickly. If you received a payment soon after a storm and later found more damage, that additional scope can usually be raised with the carrier as a supplement. If the carrier still disagrees on the amount, appraisal is one way to resolve it. Check your policy’s time limits and keep records of every contact.
It also helps to keep any local storm reports, power-outage notices or neighborhood photos from the day of the event. They place the wind at your address on that date, which matters when a carrier suggests the damage came from age or an earlier storm.
Questions about windstorm & tornado appraisal
Was the 2012 derecho treated as a hurricane under Maryland policies?
Generally no, because a derecho is not a named tropical storm. Policies define the triggers for hurricane or named-storm deductibles differently, though, so the specific wording on your declarations page controls.
Can tornado damage to my roof and siding be appraised together?
Yes. When the insurer accepts the claim and disputes the amount, the dwelling repairs, other structures and related items can all be submitted to appraisal as part of the same loss.
My adjuster says the siding is only damaged on one side. What now?
If replacement siding for that elevation can’t reasonably match the rest of the house, how much has to be replaced becomes a valuation question. An appraiser documents the product and the mismatch so the panel can decide.