Local claim risks
- Hurricane wind
- Nor’easters
- Wind-driven rain
- Storm surge
- Salt-air corrosion
Storms on record
- 1933 Chesapeake–Potomac hurricane
- Ash Wednesday nor’easter, 1962
- Superstorm Sandy, 2012
Housing mix
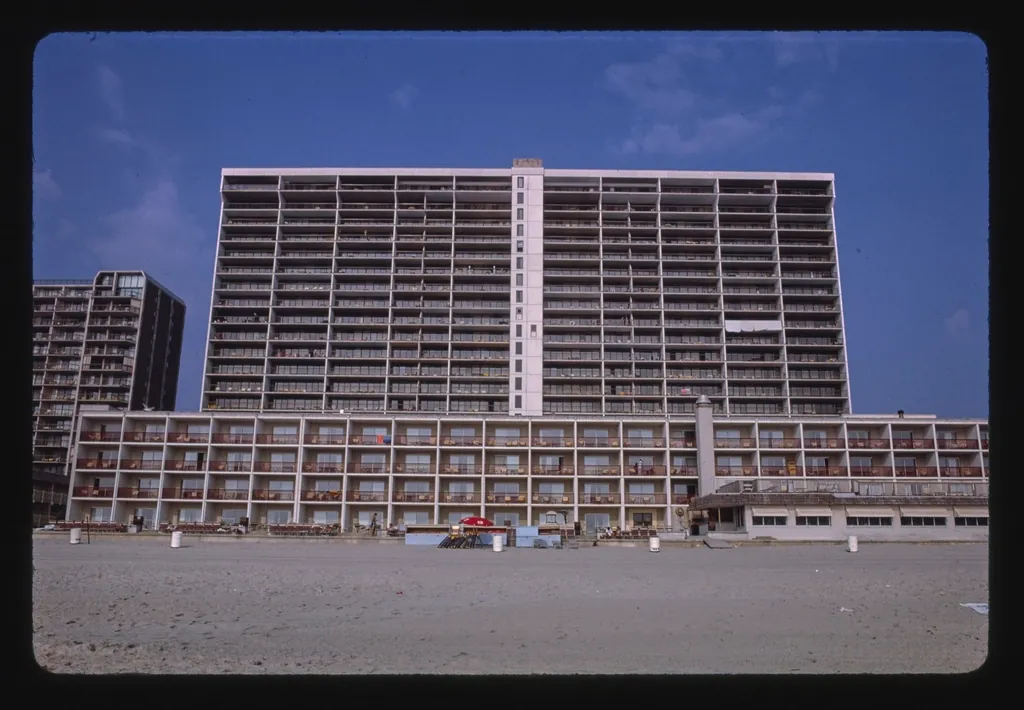
High-rise and mid-rise condominium towers along Coastal Highway, older cottages and duplexes downtown, and single-family homes and townhouses in West Ocean City, Ocean Pines and Berlin.
Neighborhoods & nearby: Downtown Ocean City, North Ocean City, West Ocean City, Ocean Pines, Berlin, Showell, Bishopville
Life on a barrier island
Ocean City sits on a narrow barrier island between the Atlantic Ocean and the coastal bays of Worcester County. The inlet at the south end of town was cut by the 1933 Chesapeake–Potomac hurricane, and the 1962 Ash Wednesday nor’easter caused severe damage along the beach. Superstorm Sandy in October 2012 brought coastal flooding to Ocean City as well. An insurance appraiser in Ocean City, MD works in one of the most storm-exposed settings in the state.
Condo towers and master policies
Much of Ocean City’s housing is in condominium towers along Coastal Highway. In these buildings, the association’s master policy usually covers the structure and common areas, while each unit owner carries an HO-6 policy for interior finishes, belongings and loss assessments. Disputes often arise when the two policies don’t line up. Our hurricane and nor’easter appraisal service covers both association and unit-owner claims.
Typical coastal estimate disputes
Wind, salt and water combine in coastal claims, and carriers frequently argue over what caused which damage. Common disagreements include:
- Wind-driven rain through balcony doors and windows reclassified as surge or wear
- Hurricane deductibles applied when the trigger may not have been met
- Exterior cladding, balcony and railing repairs priced without coastal-grade materials
- Loss assessments after the association passes a large deductible on to owners
Storm surge and rising water are generally excluded from homeowners and HO-6 policies and need separate flood coverage, so separating wind from water is a central task.
Communities we serve on the coast
We inspect throughout Ocean City, from downtown to North Ocean City, and across the bridge in West Ocean City, Ocean Pines, Berlin, Showell and Bishopville. Seasonal rental properties raise additional questions about vacancy, occupancy and landlord coverage.
Salt air also takes a toll on buildings here. Carriers sometimes point to corrosion and long-term weathering to deny or reduce wind claims, especially on balconies, railings, HVAC units and metal flashings. Dated photos from before the storm, maintenance records from the association and a clear account of what changed after the event help separate sudden storm damage from gradual wear.
Single-family homes and townhouses in West Ocean City, Ocean Pines and Berlin face many of the same issues, with added questions about trees, fences and docks on the bays.
Tips for Ocean City owners
If you don’t live in your unit year-round, arrange for someone to check it after any significant storm and to photograph what they find. Ask the association for the master policy declarations and the deductible amount. Keep records of when watches and warnings were issued, since some hurricane deductibles depend on them.
Maryland Insurance Appraiser can review the carrier’s estimate for your unit or building and represent you through appraisal when the amount of loss is disputed. Coverage and deductible disputes may need a Maryland attorney.
Services for Ocean City property owners
Every service is available in Ocean City and the rest of Worcester County, including:
- Appraisal Demand Representation
- Home Insurance Appraisal
- Commercial & HOA Appraisal
- Roof & Hail Damage Appraisal
- Windstorm & Tornado Appraisal
- Hurricane & Nor’easter Appraisal
- Water Damage Appraisal
- Fire & Smoke Damage Appraisal
Ocean City claim questions
Who covers balcony door leaks in an Ocean City condo?
It depends on the association’s governing documents and master policy. Doors and windows are sometimes treated as part of the building and sometimes as the unit owner’s responsibility. Check the documents and both policies before filing.
Can I recover a hurricane deductible passed on by my association?
Many HO-6 policies include loss assessment coverage, which may pay part of an assessment for a covered loss, subject to limits and conditions. Review that section of your policy and ask your carrier how it applies.